Big news for Postal Life Insurance customers! 📢
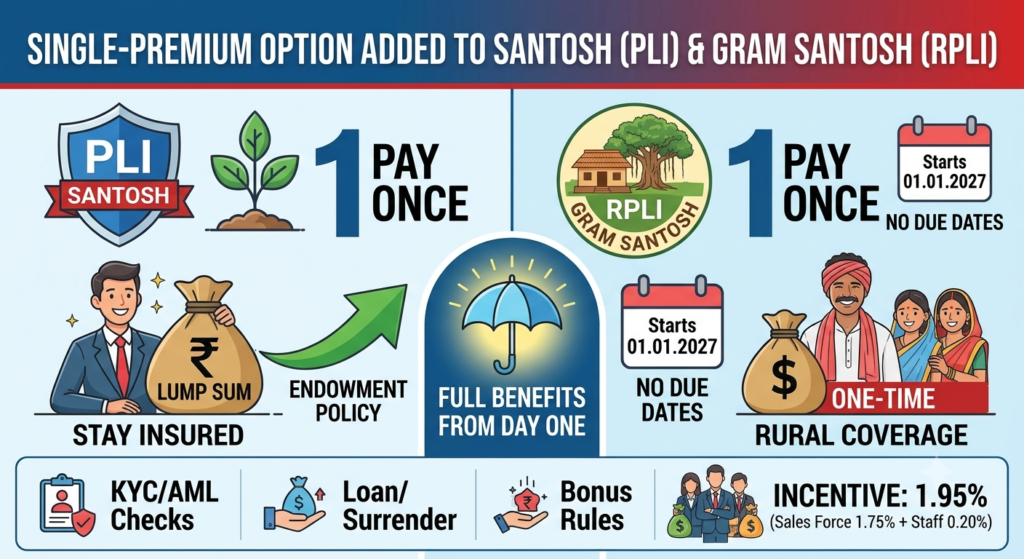
The Directorate of Postal Life Insurance has issued an Office Memorandum dated 12.11.2026. It adds a new Single-Premium Payment Option to two popular endowment policies:
- 🛡️ Santosh under Postal Life Insurance (PLI)
- 🌾 Gram Santosh under Rural Postal Life Insurance (RPLI)
👉 This means you can now pay the full premium in one go at the start of the policy, with no yearly or monthly premiums after that.
The facility is expected to start from 01.01.2027 through the new IMS system.
Here’s everything in simple words.
📄 OM at a glance
- OM No.: 25-01-LI/2026
- Issued by: Department of Posts, Directorate of Postal Life Insurance, Chanakyapuri, New Delhi
- Signed by: Amit Kumar Jha, Additional General Manager
- Date: 12.11.2026
- Rule: Rule 5(21) of the Post Office Life Insurance Rules, 2011
- Policies covered: Santosh (PLI) and Gram Santosh (RPLI) only
- Start date: 01.01.2027 (through IMS)
- Enclosure: Annexure-I – Single Premium Rate Tables
🤔 Who is this for?
This option is made for people who have a lump sum of money (like a bonus, retirement money or savings) and want to invest it in a PLI/RPLI endowment policy at once.
✅ No need to remember premium due dates ✅ No risk of policy lapsing due to missed premiums ✅ Full cover from day one
📜 Main rules of the Single-Premium Option
- 💰 Pay everything at once: The full premium for the chosen Sum Assured and term is paid as one lump sum at the start, as per the rate table.
- 🆕 Only for new policies: It’s available only when buying a new policy. An existing regular-premium policy cannot be converted to single premium.
- ➖ Not the same as advance premium: Single premium is different from paying premiums in advance during the policy.
- 📋 Same benefits: Policy terms, Sum Assured limits, maturity benefit, death benefit and loan rules of Santosh/Gram Santosh stay the same.
- 💸 Surrender: Existing surrender value factors apply to the full Sum Assured, after the minimum period. The policy is treated as fully paid-up from day one.
- 🎁 Bonus: Existing bonus rules apply. Bonus support for single-premium policies will be reviewed at each actuarial valuation.
- 🩺 Medical rules: Normal medical/non-medical underwriting rules apply. The total Sum Assured you hold across all PLI/RPLI policies will be counted.
- ✍️ Health declaration: It will be verified, and the rules on non-disclosure still apply.
🔐 Strict KYC and safety checks
Because a big amount is paid in a single transaction, all Circles must strictly follow:
- ✅ KYC rules
- ✅ Anti-Money Laundering (AML) rules
- ✅ Counter Financing of Terrorism (CFT) rules
The Consulting Actuary has also suggested safeguards to protect the PLI Fund (POLIF) and RPLI Fund (RPOLIF):
- 📈 Single-premium money to be invested mostly in long-dated Government bonds.
- 📊 Single-premium business to be tracked separately for actuarial valuation.
- 🔍 Death claims in the first 3 years (especially the first 2) will be reviewed closely.
- 🔄 Surrenders will be monitored, and surrender factors may be revised if needed.
- ⚖️ The volume of business will be watched in the early period.
🧮 Sample single premiums (from Annexure-I)
The rate tables give the single premium for each age at entry (19–55) and maturity age (35, 40, 45, 50, 55, 58, 60).
- PLI (Santosh): rates are for ₹5,000 Sum Assured
- RPLI (Gram Santosh): rates are for ₹1,000 Sum Assured
🛡️ PLI – Santosh (maturity at age 60)
| Age at entry | Rate per ₹5,000 SA | Approx. single premium for ₹1 lakh SA |
|---|---|---|
| 25 | ₹2,315.46 | ₹46,309 |
| 30 | ₹2,602.51 | ₹52,050 |
| 35 | ₹2,927.00 | ₹58,540 |
| 40 | ₹3,357.84 | ₹67,157 |
| 45 | ₹3,857.48 | ₹77,150 |
🌾 RPLI – Gram Santosh (maturity at age 60)
| Age at entry | Rate per ₹1,000 SA | Approx. single premium for ₹1 lakh SA |
|---|---|---|
| 25 | ₹483.16 | ₹48,316 |
| 30 | ₹560.66 | ₹56,066 |
| 35 | ₹633.57 | ₹63,357 |
| 40 | ₹730.71 | ₹73,071 |
| 45 | ₹831.64 | ₹83,164 |
💡 The “₹1 lakh” amounts are worked out by us from the official rates, for easy understanding only. The actual premium will be calculated by IMS at the time of the proposal.
👉 Simple rule: The younger you are and the longer the term, the lower the single premium.
💼 Incentive for sales force and staff
The total incentive for single-premium business is 1.95% of the single premium actually received.
| Who gets it | Incentive (% of single premium) |
|---|---|
| Sales Force (agents, etc.) | 1.75% |
| Promotional officers/staff | 0.20% |
| – DO PLI | 0.06% |
| – SDH | 0.04% |
| – MO | 0.02% |
| – ASP HQ | 0.06% |
| – DH | 0.02% |
- 🖥️ An extra 0.05% Technical Monitoring Incentive goes to CEPT, Mysuru staff who build and run the facility in IMS, paid once a year.
- 💡 The incentive is paid only once, on the premium actually received, and comes from the PLI/RPLI Funds.
Example: If a customer pays a single premium of ₹50,000, the sales force gets ₹875 (1.75%).
🗓️ When does it start?
- 🚀 The option is expected to go live through IMS from 01.01.2027.
- 🛠️ CEPT Mysuru will set up premium calculation, payment, accounting and reporting before that.
- 🔎 The PLI Directorate will review the facility and incentives after 4 months of rollout.
📌 Note: PLI/RPLI services are closed from 16 to 24 November 2026 for the move to the new IMS, which goes live on 25 November 2026.
🏤 What Circles and staff must do
- ✅ CPMGs must make sure the option is properly launched in their circles.
- ✅ Sales Force and staff must be trained to explain features, benefits, eligibility and premium rules.
- ✅ Focus on customers who have lump-sum funds to invest.
- ✅ All proposals must go through IMS.
- ✅ Any problems must be reported to the PLI Directorate and CEPT Mysuru.
⏱️ Quick summary in one look
- 📜 OM No. 25-01-LI/2026, dated 12.11.2026
- 🛡️ Policies: Santosh (PLI) & Gram Santosh (RPLI)
- 💰 Pay once – no further premiums
- 🆕 New policies only – no conversion of old ones
- 📋 Same benefits, loan, bonus and surrender rules
- 🔐 Strict KYC/AML/CFT checks
- 💼 Incentive: 1.95% (Sales Force 1.75% + Staff 0.20%) + 0.05% for CEPT
- 🚀 Starts: 01.01.2027 via IMS
📚 Exam corner
PLI/RPLI questions are very common in the GDS to MTS Exam, GDS to Postman Exam, MTS to PA Departmental Exam and Postman to PA Departmental Exam.
Quick revision points:
- 📌 Santosh = Endowment Assurance (EA) under PLI
- 📌 Gram Santosh = Rural Endowment Assurance (REA) under RPLI
- 📌 Rule = Rule 5(21), Post Office Life Insurance Rules, 2011
- 📌 PLI rate table base = ₹5,000 SA | RPLI rate table base = ₹1,000 SA
- 📌 Total incentive = 1.95% | Sales Force = 1.75%
- 📌 Start date = 01.01.2027
Preparation tips:
- ✅ Read India Post Circulars and India Post Latest News every day.
- ✅ Revise POLI Rules 2011 from good India Post Study Material.
- ✅ Practise India Post GK and India Post Quiz questions.
- ✅ Solve GDS to MTS Previous Year Question Papers and MTS to PA Previous Year Question Papers.
- ✅ Join GDS to MTS Online Classes, MTS to PA Online Classes or Postman to PA Online Classes for full guidance.
❓ FAQs
Q1. What is the new Single-Premium Option? It lets you pay the full premium of a Santosh (PLI) or Gram Santosh (RPLI) policy in one lump sum at the start, with no further premiums.
Q2. Which policies have this option? Only Santosh (PLI) and Gram Santosh (RPLI).
Q3. Can I convert my existing policy to single premium? No. It’s only for new policies.
Q4. When will it start? It’s expected to start through IMS from 01.01.2027.
Q5. Will I get bonus on a single-premium policy? Yes, existing bonus rules apply. Bonus support will be reviewed at each actuarial valuation.
Q6. Can I take a loan or surrender the policy? Yes. Existing loan and surrender rules apply, and the policy is treated as fully paid-up from the start.
Q7. Is a medical exam needed? Normal medical/non-medical rules apply, based on your total Sum Assured across all PLI/RPLI policies.
Q8. How much incentive will agents get? The Sales Force gets 1.75% of the single premium received. Promotional staff together get 0.20%.