Published on: 15 August 2026 Order Dated: 14 August 2026 Category: India Post Circulars · PLI / RPLI · India Post Latest News
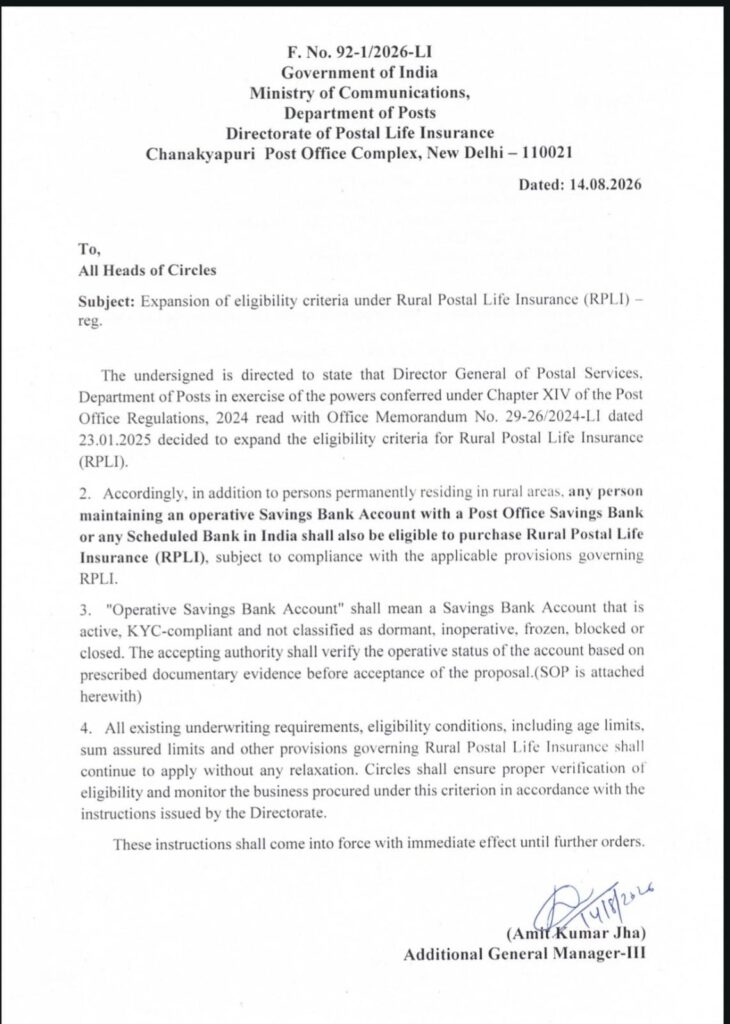
The Directorate of Postal Life Insurance has issued an order that meaningfully widens who can buy Rural Postal Life Insurance (RPLI).
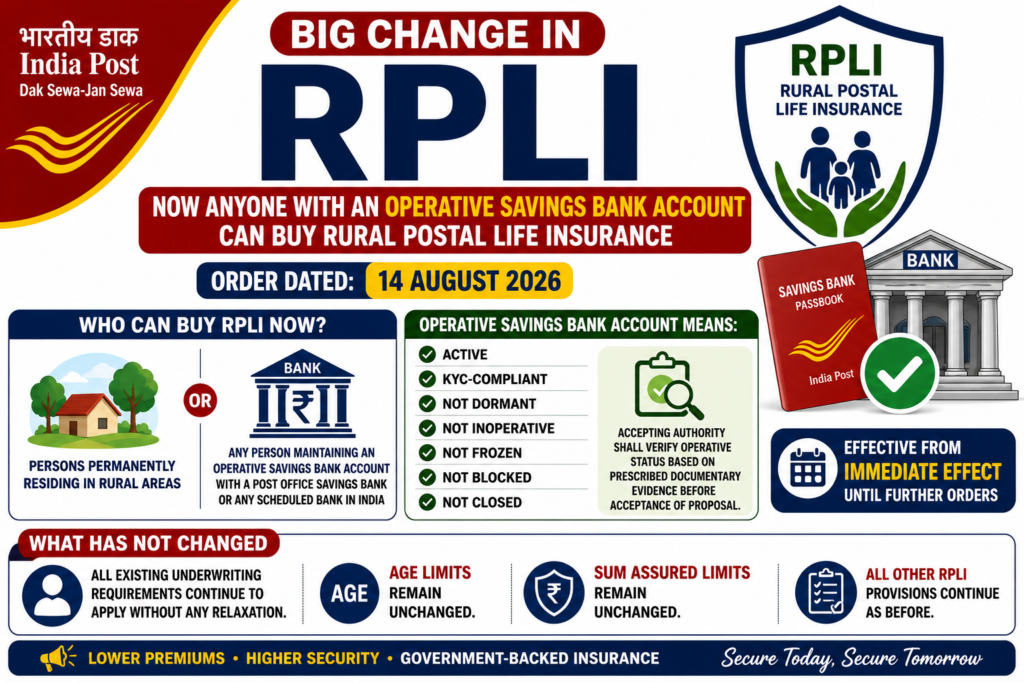
Until now, RPLI was essentially for people permanently residing in rural areas. From this order onwards, any person maintaining an operative Savings Bank Account — with a Post Office Savings Bank or any Scheduled Bank in India — is also eligible.
The order is effective immediately.
Order Details
| Item | Details |
|---|---|
| Letter No. | F. No. 92-1/2026-LI |
| Dated | 14.08.2026 |
| Issued by | Directorate of Postal Life Insurance, Chanakyapuri Post Office Complex, New Delhi – 110021 |
| Signed by | Shri Amit Kumar Jha, Additional General Manager-III |
| Addressed to | All Heads of Circles |
| Subject | Expansion of eligibility criteria under Rural Postal Life Insurance (RPLI) |
| Effective From | Immediate effect, until further orders |
Authority under which it was issued: The Director General of Postal Services exercised powers conferred under Chapter XIV of the Post Office Regulations, 2024, read with Office Memorandum No. 29-26/2024-LI dated 23.01.2025.
What Exactly Has Changed
Here is the change in one line.
Before: RPLI was for persons permanently residing in rural areas.
Now: RPLI is for persons permanently residing in rural areas PLUS any person maintaining an operative Savings Bank Account with a Post Office Savings Bank or any Scheduled Bank in India.
The second category is subject to compliance with the applicable provisions governing RPLI.
This is a substantial widening. A savings bank account is something the vast majority of Indians already have — so the practical effect is that RPLI’s customer base is no longer tied to a rural address.
What Counts as an “Operative Savings Bank Account”
The order defines this term precisely, and the definition matters because it is what the accepting authority will check.
An Operative Savings Bank Account means an account that is:
- Active
- KYC-compliant
- Not classified as dormant
- Not classified as inoperative
- Not frozen
- Not blocked
- Not closed
A dormant account or one with incomplete KYC will not qualify. If a customer’s account fails any of these tests, the proposal cannot be accepted under this new criterion.
Verification Is Mandatory
The order states that the accepting authority shall verify the operative status of the account based on prescribed documentary evidence before acceptance of the proposal.
A Standard Operating Procedure (SOP) is attached to the original order. The SOP was not part of the copy circulated here, so field staff should obtain the complete order with the SOP from their Divisional or Circle office before accepting proposals under this criterion. Do not work from the covering page alone.
What Has NOT Changed — Read This Carefully
This is the part that will trip people up if they skim.
The order is explicit: all existing underwriting requirements, eligibility conditions and other provisions governing RPLI continue to apply without any relaxation. Specifically named:
- Age limits — unchanged
- Sum assured limits — unchanged
- All other underwriting requirements — unchanged
So this is an expansion of who can apply, not a loosening of the product rules. The RPLI sum assured ceiling still applies. The age bands still apply. Medical and non-medical underwriting rules still apply.
If a customer expects RPLI on relaxed terms because of this order, that expectation is wrong.
Responsibility Placed on Circles
Two clear instructions to Circles:
- Ensure proper verification of eligibility
- Monitor the business procured under this criterion in accordance with instructions issued by the Directorate
The second point is worth noting. The Directorate has said it will be watching business sourced under this new route specifically. That suggests scrutiny on whether the operative-account condition is being genuinely verified rather than assumed.
For field staff, the practical meaning is simple: keep the documentary evidence on record. If business under this criterion is later reviewed, the proposal file needs to stand on its own.
Why This Matters
For Customers
- RPLI premiums are lower than comparable PLI plans, so wider eligibility gives more people access to a low-cost, government-backed life insurance option
- No rural residence requirement means people who moved to towns and cities, or who never lived rurally, can now consider RPLI
- The entry condition is one most people already meet — an active, KYC-compliant savings account
For Postal Staff, GDS and Field Officers
- The addressable market for RPLI has widened considerably overnight
- Existing POSB account holders are now a natural pool to approach — you can identify eligible customers from accounts you already service
- Scheduled bank account holders qualify too, so the customer does not need to bank with the post office
- But the verification burden is on you. Accepting a proposal without checking the operative status of the account is where problems will arise later.
For Departmental Exam Aspirants
PLI and RPLI feature in the syllabus of several departmental exams, including LDCE for Inspector Posts (Post Office Life Insurance Scheme 2011 and amendments compiled as SANKALAN, and PLI-CIS under Information Technology).
Since circulars issued up to 31 December of the year preceding the exam form part of the LDCE IP syllabus, this order dated 14.08.2026 falls within the range for the 2027 exam cycle, not the September 2026 exam. Still worth noting now — RPLI eligibility is exactly the kind of point that turns into an objective question.
Practical Checklist for Field Staff
Before accepting an RPLI proposal under the new criterion:
- Confirm the customer holds a Savings Bank Account with a Post Office Savings Bank or any Scheduled Bank in India
- Verify the account is active and KYC-compliant
- Confirm it is not dormant, inoperative, frozen, blocked or closed
- Collect the prescribed documentary evidence and keep it on the proposal file
- Follow the SOP attached to the original order — obtain the full order from your Divisional office
- Apply all normal RPLI underwriting rules — age, sum assured, medical requirements — with no relaxation
- Record the proposal correctly so business under this criterion can be identified during monitoring
Frequently Asked Questions
Q. Can a person living in a city now buy RPLI? Yes, provided they maintain an operative Savings Bank Account as defined in the order and meet all other RPLI conditions.
Q. Does the savings account have to be with the post office? No. A Post Office Savings Bank account or an account with any Scheduled Bank in India qualifies.
Q. My customer’s account is dormant. Can they still apply? Not under this criterion. The account must be active and not classified as dormant, inoperative, frozen, blocked or closed.
Q. Have the RPLI age limit and sum assured limit changed? No. The order specifically says all existing underwriting requirements, age limits and sum assured limits continue to apply without any relaxation.
Q. From when is this applicable? With immediate effect from the date of the order, 14.08.2026, until further orders.
Q. Where do I find the SOP? It is attached to the original Directorate order. Obtain the complete order from your Divisional or Circle office before accepting proposals under this criterion.
Q. Does the rural residence route still exist? Yes. Persons permanently residing in rural areas remain eligible as before. The savings-account route is an addition, not a replacement.
Related Guides on Our Website
- PLI and RPLI Plans — Premium, Sum Assured and Maturity Explained
- India Post Circulars and Latest News
- LDCE Inspector Posts 2026 — Notification, Syllabus and Apply Online Guide
- GDS to MTS Departmental Exam — Syllabus, Notification and Online Classes
- GDS to Postman / Mail Guard Coaching, Syllabus and Study Material
- MTS to PA and Postman to PA Online Classes
- Postal Assistant (PA/SA) Exam Preparation and Question Bank
- India Post Previous Year Question Papers and Mock Tests
Final Word
This is one of the more consequential PLI Directorate orders in recent times. RPLI has always been a strong product held back by a narrow eligibility gate. That gate has now been widened to almost anyone with a working bank account.
For field staff, the opportunity is real — but so is the verification duty. Do the account check properly and keep the evidence. The Directorate has said in the same breath that it will monitor business sourced this way.
Note: This summary is based on Directorate letter F. No. 92-1/2026-LI dated 14.08.2026. The SOP referred to in the order is not reproduced here. For acceptance of proposals, always rely on the complete original order and SOP received through your Circle or Divisional office.