If you are a GDS, Postman, MTS, Postal Assistant or a PLI agent, you already know one thing very well — most PLI proposal forms come back from the office because of small mistakes.
Wrong photo place. Address left half-filled. Premium amount written without tax. Nominee minor but appointee column empty. And the whole form goes back for correction.
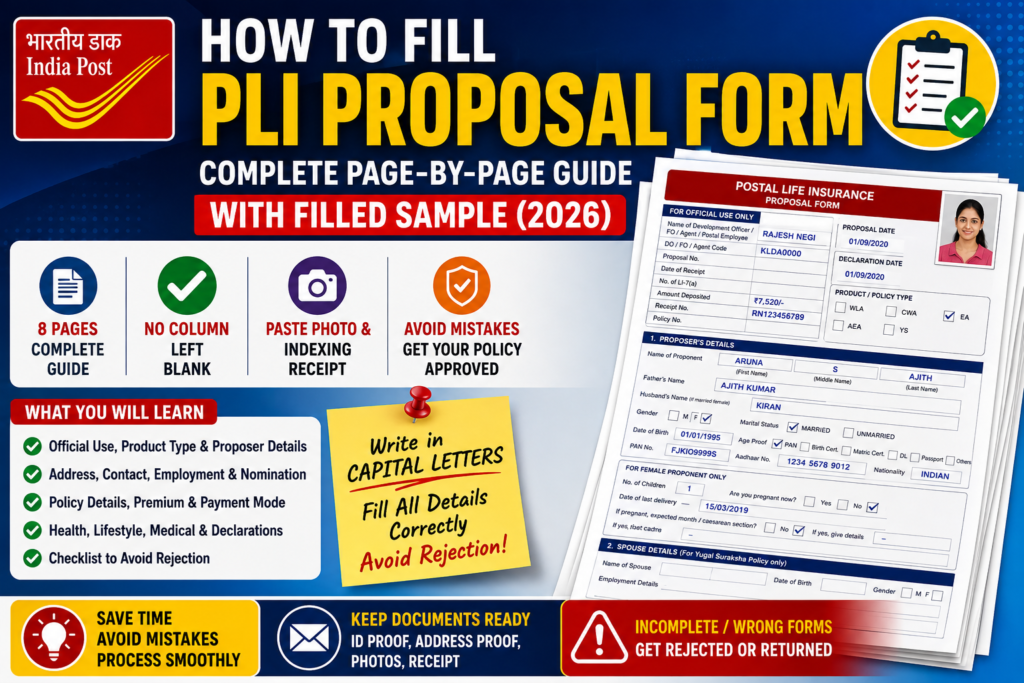
This post explains the PLI Proposal Form page by page, in simple words, using an actual filled sample format. Read it once before you fill your next form. It will save you a second visit to the post office.
First, the Basic Rules
Before writing a single word on the form, remember these:
- Write everything in CAPITAL LETTERS. This is printed on the form itself, and offices are strict about it.
- Total 8 pages. Do not skip any page, even if it looks blank.
- No column should be left un-answered. Blank columns are the number one reason for rejection.
- Questions 12, 12.1, 13 and 14 are only for Sum Assured above ₹20 lakh. If your policy is below that, leave these portions as they are.
- Affix proponent’s recent passport size photo in the top right box. Spouse’s photo is needed only for Yugal Suraksha (YS) proposals.
- Paste the indexing receipt in the “For Official Use Only” box.
Page 1 — Official Use, Product Type and Proposer’s Details
For Official Use Only (Top Box)
- Name of Development Officer / FO / Agent / Postal Employee — write the name of the agent or salesman. Eligible people include ASP, IPO, PM, PA, SA, Postman, Mail Guard, MTS, GDS BPM, GDS DA and GDS MC.
- DO/FO/Postal Employee/GDS/Agent/Sales Force Code — the agent code, e.g.
KLDA0000. - Proposal No., Date of Receipt, No. of LI-7(a), Amount deposited, Receipt No. and Policy No. are filled by the office, not by you.
Proposal Date and Declaration Date
Both in DD/MM/YYYY format. In the sample both are 01/09/2020. Keep them the same date.
Product / Policy Type
Tick any one:
- WLA — Whole Life Assurance
- CWA — Convertible Whole Life Assurance
- EA — Endowment Assurance (ticked in the sample)
- AEA — Anticipated Endowment Assurance
- YS — Yugal Suraksha
1. Proposer’s Details
- Name of Proponent — First, Middle and Last name in separate boxes. Sample:
ARUNA S AJITH - Father’s Name —
AJITH KUMAR - Husband’s Name — only if the proponent is a married female. Sample:
KIRAN - Gender — tick M or F
- Marital Status —
MARRIEDorUNMARRIED - Date of Birth —
01/01/1995 - Age Proof — tick any one: Birth Certificate, Matriculation Certificate, Driving License, Passport, PAN, Service Register extract (for Govt. employees) or Defence ID card. Sample uses PAN —
FJKIO9999S - Aadhaar No. and Nationality —
INDIAN
For Female Proponent Only
This part is for female proponents and female spouse in Yugal Suraksha:
- Number of children
- Are you pregnant now — Yes / No
- Date of last delivery
- If pregnant, expected month of delivery
- Any abortion, miscarriage or caesarean section — give details if yes
2. Spouse Details
Fill this only for Yugal Suraksha policy. For all other products, leave it blank.
Page 2 — Address, Contact, Employment and Nomination
3. Proposer’s Address Details
- Communication Address — fill completely. House, Village, City, State, Taluka, District, Country and PIN. Do not leave PIN blank.
- Permanent Address — fill exactly as written in the address proof you are attaching. If both addresses are same, tick the box provided.
Most rejections happen here. Half-written address means the policy bond will not reach the customer.
4. Proposer’s Contact Details
- Phone No. with STD code
- Mobile No.
- E-mail ID — mark this clearly: email ID is compulsory if the customer wants online premium payment. Without email, no online payment, no IPPB/India Post Payments Bank auto-debit convenience.
5. Proposer’s Employment Details
- Occupation — tick one: Central Govt, State Govt, PSU, Railway, Bank, Telecom, Contractual, Joint Venture, Defence, Para Military Force, Cooperative Society, Deemed University / Educational Institution, or Other
- Name of Organization — full department or organization name
- Designation — current post of the employee
- Date of Entry in Service —
01/01/2015 - Designation of Immediate Superior
- PAN No. —
FJKIO9999S - Monthly Income —
₹20000 - DDO Code
- Office Address — complete address with pincode
- Office Phone No. and Official E-mail ID
- Qualification — tick one: Post Graduate, Graduate, Diploma, Se. Sec. Education, High School, Middle Class, Primary Education, Illiterate or Other
6 and 6A — Married Women’s Property Act 1874
- If the policy is taken under MWPA 1874, give beneficiary details on a separate page — name, date of birth, relationship, whether minor, and share percentage. Maximum three beneficiaries.
- For a trust, give trust details, trustee name, relationship and contact details.
- Important: nomination is NOT allowed in MWPA cases. So if you fill section 6, do not fill section 7.
7. Nomination Details
Under Section 39 of the Insurance Act 1938.
- Maximum three nominees allowed
- Give First, Middle and Last name
- Tick relationship: Brother, Sister, Son, Daughter, Mother, Father, Spouse, Father-in-law, Mother-in-law or Others
- Sample:
ASWIN AK, relationship Son
Page 3 — Nominee Share, Appointee and Address
- Share percentage — total of all nominees must come to 100%. Sample gives
100%to the single nominee. - Gender and Date of Birth —
01/01/2016 - Age —
04 Years - Communication Address of nominee — complete with pincode
- Second and Third Nominee blocks — fill only if there is more than one nominee
Appointee Details — Do Not Miss This
If the nominee is a minor, the appointee column is compulsory.
In the sample, the nominee is a 4-year-old son, so an appointee is given:
- Name:
KIRAN - Relationship:
FATHER - Gender: M
- Date of Birth:
01/01/1990 - Age:
31 Years - Plus complete communication address with pincode
Forget this one column and the claim will get stuck later. Always check the nominee’s age first.
Page 4 — Existing Policies, Coverage, Premium and Health
8. Additional Policy(ies) Details
- Part i — details of other PLI / RPLI policies already held: Policy No., Type, Sum Assured, Maturity Date, and total
- Part ii — details of life, health and non-life policies of other companies: Policy No., Type, Insurer, Sum Assured, Maturity Date, and total
If there are none, write NIL. Do not leave it empty.
9. Coverage Details
- Premium Ceasing Age / Age at Maturity —
50 Years - Policy Term —
24 Years - Sum Assured —
₹10,00,000
10. Premium Details
- Premium —
₹3292 - Initial Premium Payment Mode —
CASH(options: Cash, Cheque, Credit Card, Debit Card, Salary) - Subsequent Premium Payment Mode — fill accordingly, usually Cash or Salary recovery
- Premium Payment Frequency — Monthly, Quarterly, Half Yearly or Yearly. Sample: Monthly
A very useful tip from the sample: it is better to write the full calculation on the form.
Premium        3292
Tax (GST)      + 50
-------------------
Total          3342
Writing the tax separately avoids confusion at the counter about how much cash was actually collected.
11. Proponent’s Health Information
- Are you and your spouse in sound health at present? — Yes / No
- Then answer Yes or No for each of the 15 health conditions listed:
- Tuberculosis, Asthma, Bronchitis, Blood Spitting or other respiratory disorders
- Cancer, Tumor, Cysts or any other growth
- Paralysis
- Insanity
- Heart and lung disease, chest pain, palpitation, rheumatic fever, heart attack, shortness of breath
- Kidney disease, prostate, hydrocele, urinary system
- Brain disease, depression, mental / psychiatric ailment, multiple sclerosis, stroke, Parkinsonism
Page 5 — Remaining Health Questions and the ₹20 Lakh Sections
Continuing the same list:
- HIV Positive / AIDS or any sexually transmitted disease
- Hepatitis B, C or A
- Epilepsy
- Nervous disorder, gastritis, stomach or duodenal ulcer, hernia
- Symptoms or ailment relating to liver or reproductive system
- Leprosy
- Any physical deformity or handicap
- Any other serious disease
Then:
- c. Family history — has any family member (father, mother, brothers, sisters), living or dead, suffered from a hereditary or infectious disease like insanity, epilepsy, gout, asthma, tuberculosis, cancer or leprosy? Tick accordingly and give details if Yes.
- d. Medical leave or hospitalization in the last 3 years — give kind of leave, period, ailment, hospital name and period of hospitalization.
- e. Any physical deformity or congenital birth defect — Yes / No, with type if applicable.
- f. Particulars of family doctor, if any.
12. Additional Health Information — Only Above ₹20 Lakh
This entire section is required only if Sum Assured or Aggregate Sum Assured is above ₹20 lakh. It covers tests undergone, diabetes, blood pressure, oncologist referral, thyroid, angioplasty and similar.
If your policy is ₹10 lakh like the sample, skip it.
Page 6 — Female Health, Habits, Suitability and Declaration
12.1 Additional Health Information for Female Proponent
Again, only for Sum Assured exceeding ₹20 lakh. Covers abortion or ectopic pregnancy history, gynaecological investigations, mammogram or biopsy, and related consultations.
13. Personal Habits Impacting Health
Only above ₹20 lakh. Covers smoking or tobacco, alcohol, drugs and any other habit affecting health, along with whether frequently or occasionally.
14. Suitability Analysis
Only above ₹20 lakh. It has four parts:
- Affordable contribution — yearly and monthly, projected up to 30 years
- Income and expenditure — current and projected
- Financial details — value of savings and assets
- Family and dependent details — name, gender, relationship, date of birth, occupation, financial dependency
15. Declaration of Proponent / Spouse
The declaration confirms that:
- No earlier insurance proposal on this life was adversely treated by any insurance company
- All statements made are true to the best of knowledge and belief
- If any untrue statement or concealment is found, all premium paid will be forfeited and the contract becomes null and void
- The life is insured from the date the proposal is accepted
- The terms and conditions of PLI have been read, received and explained in the applicant’s own language
Spouse signature is required only in Yugal Suraksha policies.
Page 7 — Surrender Rules, Signature and Agent Certification
Surrender Value Declaration — Read This Properly
These points are declared by the proponent, and every agent should explain them clearly:
- Surrender is not admissible before completion of 36 months of the policy. If surrendered within 36 months, the amount deposited is forfeited.
- On surrender, the policy gets proportionate bonus on the reduced sum assured up to the date premium was paid. But no bonus is payable before completion of 5 years.
- A discontinued policy does not attract bonus from the date premium is stopped.
- Reduced sum assured = Sum Assured × Number of instalments paid ÷ Total number of premiums payable.
- Surrender value = (Reduced sum assured + proportionate bonus) × surrender factor for the attained age on the date of surrender.
- Surrender is applicable for WLA, CWA, EA and YS policies.
Part B — Hypertension and Diabetes Declaration
- Write name, e.g.
ARUNA S AJITH, son/wife/daughter ofKIRAN, aged26years - Then select one of the two options:
- Not suffering from Hypertension and Diabetes and not taking any treatment, OR
- Suffering from Diabetes / Hypertension for the last ___ years, but under control with proper medical advice and medication, with no complication so far
Strike off the option that does not apply.
Part C and Signatures
- Fee agreed for medical examination if the proposal is not accepted
- Proponent’s Signature — compulsory
- Spouse’s Signature — Yugal Suraksha only
- Date:
01 September 2020
16. Certificate of Immediate Superior
Very important point, and many people don’t know this:
This certificate is NOT mandatory. Instead, collect a self-attested copy of the last month’s pay slip and the departmental ID card.
This saves a lot of running around for the customer.
17. To Be Filled by DO / FO (PLI) / Agent / Sales Force
For Sum Assured up to ₹20 lakh, the agent certifies that:
- The information in the proposal form was furnished by the proponent
- It was signed or thumb-impressed in the agent’s presence
- All columns are complete and correct, and no question is left un-answered
- The proposal is recommended for acceptance
Fill: Name of Agent / Salesperson, Code No. / ID (KLDA 0000), Date (01/09/2020) and Agent’s Signature.
For proposals above ₹20 lakh, an extra table has to be filled — life stage, protection needs, appetite for risk, policy recommended, commitment details, whether risk elements were explained, why the product suits the proposer, and whether the product is based on need, demand or agent’s recommendation.
Page 8 — Final Agent Entries, Acknowledgement and Medical Tests
Details to Be Entered in All Cases by Agent / Sales Person / Broker
- Policy Type:
EA - Sum Assured:
1000000 - Age at Entry:
26 - Premium Rate:
₹3292 - Receipt LI-7(a) No. and Date
- Amount collected from proponent
- Name and Code of Medical Officer
- Post Office where payment is being deposited — write the name of the post office where indexing is being done
Certification and Acknowledgement
- The agent certifies that the recommended product is suitable, and that features, terms, exclusions, premium commitments and charges were fully explained.
- The Proposer’s Acknowledgement below it needs the proponent’s signature again, confirming that the product was explained and believed suitable.
18. Medical Examiner’s Certificate
Filled by the Medical Officer. The examiner either recommends acceptance or declares the proponent medically unfit. Proponent’s signature is required here too. Spouse signature only in Yugal Suraksha.
Note for Medical Officer
- If the proponent is overweight or has a doubtful family history — ECG and chest scanning report required
- If the proponent is underweight with family history of TB — chest X-ray required
- Expenses of these tests are borne by the proponent
Medical Tests by Age (Standard Cases)
| Age of Proponent | Tests Required |
|---|---|
| Up to 35 years | ECG, Routine Urine Analysis, SBT 13, Hb % |
| 36 to 45 years | ECG, Routine Urine Analysis, SBT 13, Hb %, CTMT, Hemogram |
| 46 to 55 years | ECG, Routine Urine Analysis, SBT 13, Hb %, CTMT, Hemogram, Hb A1c |
| 56 years and above | ECG, Routine Urine Analysis, SBT 13, Hb %, CTMT, Hemogram, Hb A1c |
| Policy revival cases | X-ray of chest |
Extra Tests Above ₹20 Lakh — Supplementary Bio-Chemical Tests (SBT-13)
Fasting Blood Sugar, Total Cholesterol, HDL, LDL, S Triglycerides, S Creatinine, Blood Urea Nitrogen (Albumin, Globulin), AG Ratio, S Bilirubin (Direct, Indirect, Total), SGOT (AST), GGTP (ALT), S Alkaline Phosphate, Hbs AG (Australia antigen) and Elisa for HIV.
Top 10 Mistakes That Get PLI Forms Rejected
- Writing in small letters instead of CAPITAL letters
- Photo not affixed, or spouse photo missing in Yugal Suraksha
- Communication or permanent address left incomplete, PIN missing
- Email ID left blank even though the customer wants online payment
- Nominee share percentage not totalling 100%
- Appointee column empty when the nominee is a minor
- Premium written without showing the tax calculation
- Health questions left blank instead of ticking Yes or No
- Existing policy details left empty instead of writing NIL
- Agent code, agent signature or post office name not written on page 8
Documents to Attach with the Proposal Form
- Age proof — PAN, Aadhaar, Birth Certificate, Matriculation Certificate, Passport, Driving License or Service Register extract
- Address proof matching the permanent address written on the form
- Recent passport size photograph (plus spouse photo for YS)
- Self-attested copy of last month’s pay slip
- Self-attested copy of departmental ID card
- Indexing receipt, pasted in the official use box
Frequently Asked Questions
Q. Is the Certificate of Immediate Superior compulsory in the PLI proposal form? No. It is not mandatory. A self-attested copy of the last month’s pay slip and the departmental ID card is accepted instead.
Q. Which sections are only for Sum Assured above ₹20 lakh? Sections 12, 12.1, 13 and 14. Below ₹20 lakh, these are left blank.
Q. When is an appointee required? Whenever the nominee is a minor. Give the appointee’s name, relationship, gender, date of birth, age and full address.
Q. Can I fill both nomination and MWPA beneficiary details? No. If the policy is under the Married Women’s Property Act 1874, nomination is not allowed.
Q. Is spouse signature always needed? No, only for Yugal Suraksha (YS) policies.
Q. When can a PLI policy be surrendered? Not before completion of 36 months. And no bonus is payable before completion of 5 years of the policy.
Q. Who can procure PLI business? Direct Agents, Field Officers, Development Officers and departmental employees including ASP, IPO, PM, PA, SA, Postman, Mail Guard, MTS, GDS BPM, GDS DA and GDS MC.
Final Words
The PLI proposal form looks long, but it is not difficult. It only demands attention.
Fill it in capital letters, complete every address with pincode, check the nominee’s age before deciding on the appointee, and write the premium along with the tax. Do these four things and your form will pass in the first attempt.
For every GDS, Postman and MTS working on the field, PLI is not just paperwork — it is extra incentive income and it builds your customer relationship for years. Learn the form properly once, and it stays with you for your whole career.